
Arabfields, Farah Benali, Economic Correspondent, China — China’s power transformer industry is positioning itself for further growth as electricity demand rises, renewable energy projects expand and utilities invest in upgrading ageing transmission networks. Manufacturers are also seeking a larger share of international contracts as shortages of key electrical equipment put pressure on delivery schedules in several markets.
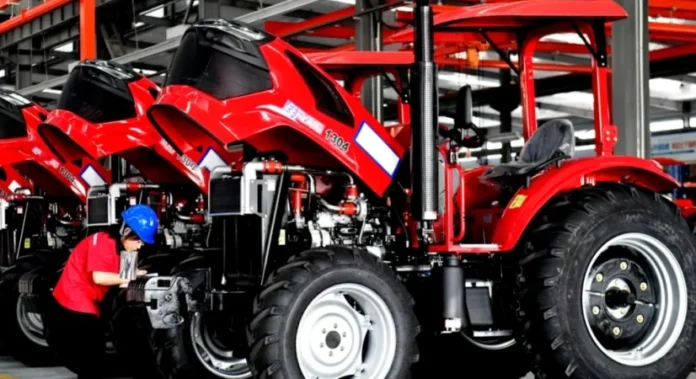
China has become a major force in global transformer manufacturing, supported by an extensive industrial supply chain, large production facilities and growing expertise in high-voltage and ultra-high-voltage transmission technology. Industry estimates published in 2026 place China’s share of global transformer production capacity at around 60%, underscoring the country’s influence over the equipment needed to move electricity from power plants to consumers.
The expansion of artificial intelligence infrastructure is adding another source of demand. Data centres require reliable electricity supplies, dedicated substations and transformers capable of handling substantial loads. At the same time, solar and wind projects are creating additional requirements for grid connections, voltage management and power distribution equipment.
For electrical contractors and utility operators, securing transformers has become an increasingly important part of project planning. A delayed delivery can postpone the commissioning of a substation or prevent a renewable energy facility from connecting to the grid. Manufacturers that can demonstrate reliable production schedules, consistent quality and access to essential components are therefore well positioned to compete for new orders.
Among the established Chinese suppliers, TBEA, China XD Electric, Henan Pinggao Electric and CHINT Group serve different segments of the electricity infrastructure market. Their activities span power transformers, transmission equipment, switchgear and distribution systems. Jiangsu Dinghong Power, meanwhile, illustrates the role of manufacturers seeking international business through a combination of electrical equipment production, engineering services and products designed for overseas certification requirements.
The companies operate in a competitive market where technical specifications and project experience can matter as much as price. Large utility contracts often require extensive testing, compliance with local electrical standards and detailed documentation before equipment can be accepted. Overseas buyers must also consider installation support, spare-parts availability and warranty arrangements, particularly for equipment expected to operate for decades.
Market projections indicate that the growth opportunity could remain substantial. One industry estimate valued China’s transformer market at approximately $18.91 billion in 2026 and forecasts that it could reach $29.52 billion by 2031. That would represent annual compound growth of roughly 9.3%, although the forecast depends on infrastructure investment, procurement activity and the pace of grid modernisation.
The transition towards cleaner electricity is expected to remain a major driver. Renewable energy projects often require new substations and upgraded transmission lines to move electricity from generation sites to population centres and industrial users. Investment in ultra-high-voltage networks could provide additional opportunities for manufacturers capable of producing large, technically demanding transformers.
Digitalisation is another emerging priority. Utilities are increasingly interested in equipment that supports remote monitoring, predictive maintenance and more efficient management of electricity networks. Manufacturers able to combine conventional transformer engineering with digital monitoring technologies may gain an advantage as operators seek to reduce downtime and improve the reliability of their assets.
However, the industry’s prospects are not without challenges. Demand for specialised electrical steel, bushings and other critical components can affect manufacturing costs and delivery schedules. International suppliers must also navigate different certification requirements, trade policies and technical standards. For smaller manufacturers, establishing a credible overseas service network can be difficult and expensive.
For buyers in Africa, Asia and other developing markets, Chinese suppliers may offer an attractive combination of manufacturing capacity and competitive pricing. Yet procurement decisions require careful evaluation of technical compliance, independent test results, factory capabilities and after-sales support. The lowest initial quotation does not necessarily translate into the lowest lifetime operating cost.
Looking towards 2027, continued investment in electricity networks, renewable energy and data centres could support further demand for Chinese transformers. Manufacturers with proven testing capabilities, dependable supply chains and experience in international projects are likely to be better positioned to secure repeat orders.
The longer-term outlook will depend on whether electricity investment continues at the pace anticipated by industry forecasts. If grid expansion and digital infrastructure projects maintain their momentum, transformer manufacturers could benefit from years of sustained demand. For the companies competing in this market, the challenge will be to convert growing order opportunities into reliable deliveries while maintaining quality and controlling costs.