
Arabfields, Naïla Mokhtari, Correspondent, São Paulo, Brasil — Brazilian soybean prices have remained relatively firm in November, supported by a stronger US dollar and favourable export conditions, even as international markets face uncertainty over global supply and demand. The currency movement has provided an important cushion for domestic producers ahead of the 2026/27 harvest.
The Brazilian real has weakened against the US currency, with the dollar trading above R$5.80, approximately 17% higher since the country’s recent elections. The depreciation has improved the competitiveness of Brazilian agricultural exports while increasing the value of international sales when converted into local currency.
In the port of Santos, soybean contracts for March delivery have approached R$155 per 60-kilogram bag. In Dourados, Mato Grosso do Sul, prices have climbed to approximately R$130 per bag, representing an increase of around 10% since October.
For farmers, the stronger market offers some relief after months of uncertainty over production costs, financing conditions and international commodity prices. Producers preparing for the new harvest must nevertheless balance attractive selling opportunities against the possibility of further market movements.
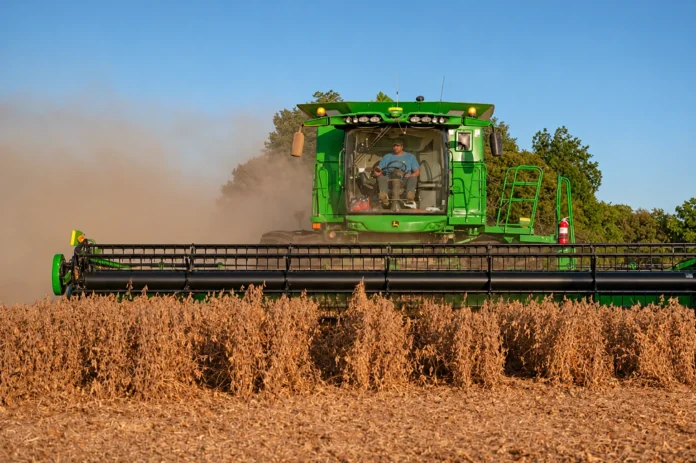
Brazil remains one of the world’s largest soybean suppliers, and expectations for the coming season are relatively optimistic. Agricultural consultancy AgRural estimates that national soybean production could reach 182.8 million tonnes in the 2026/27 season, surpassing the previous record of 180.4 million tonnes.
Planting has also progressed faster than during the previous season. According to figures from Brazil’s National Supply Company, known as Conab, approximately 66.8% of the expected soybean area had been planted by November 6, compared with 59% during the corresponding period last year.
However, favourable production prospects have not translated into an equally rapid expansion of cultivated land. The planted area is expected to reach approximately 49.18 million hectares, an increase of just 1.2%. This represents the slowest expansion in nearly two decades, reflecting tighter credit conditions and higher production costs.
For smaller farming operations, access to financing remains a significant concern. Higher borrowing costs can restrict investment in machinery, fertilisers and agricultural technology, forcing producers to rely more heavily on existing resources. The stronger dollar also has a downside, as imported fertilisers and other agricultural inputs become more expensive.
International market developments are adding another layer of uncertainty. Soybean futures in Chicago have faced pressure from expectations of abundant South American supplies, although adjustments to US production and inventory estimates have provided occasional support.
China’s purchasing activity will remain particularly important for Brazil. As the leading destination for Brazilian soybean exports, Chinese demand could determine how effectively the country absorbs the expected increase in production during the coming marketing season.
The exchange rate is therefore likely to remain a central factor in domestic price formation over the next several months. If the dollar stays above R$5.80, Brazilian producers could continue benefiting from relatively competitive export prices, even if international soybean quotations experience moderate corrections.
Looking towards the first half of 2027, the market is expected to remain sensitive to weather conditions across Brazil and Argentina. The development of El Niño could influence rainfall distribution, particularly in regions where agricultural production depends heavily on seasonal precipitation. Any significant deterioration in growing conditions could reduce expected yields and provide additional support for international prices.
Based on current production estimates, Brazil could harvest more than 182 million tonnes of soybeans, strengthening its position in global agricultural trade. However, a record crop could also increase domestic supply pressure, particularly if export demand fails to absorb the additional volume at the expected pace.
For producers, the coming months will involve difficult decisions about when to sell, how much to store and whether to secure prices through forward contracts. A favourable exchange rate may encourage early commercialisation, but uncertainty over weather and international demand could make some farmers reluctant to commit their entire production in advance.
Brazil’s soybean market is consequently entering a decisive period. The weaker real is currently supporting domestic prices, but the sustainability of this trend will depend on the interaction between currency movements, export demand, production costs and the performance of the new harvest.
While the outlook remains cautiously positive, the next few months will determine whether stronger export revenues can translate into improved farm profitability across the country’s main agricultural regions.